A group of senior creditors to JetBlue Airways Corp. has enlisted financial adviser PJT Partners and law firm Akin Gump Strauss Hauer & Feld as the airline faces cash burn and higher fuel costs. The move comes as its bonds and shares fall sharply.
Notes due 2031 dropped to 42 cents on the dollar Thursday, then recovered into the mid-40s Friday. They had traded near 80 cents earlier this month.
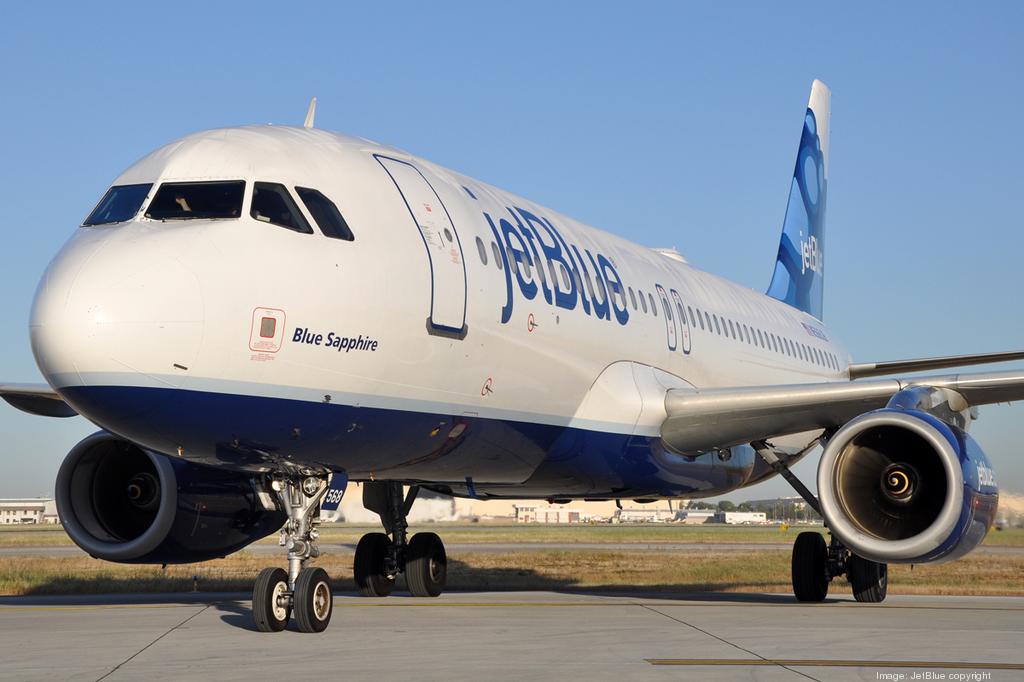
JetBlue shares fell nearly 10% Thursday, closing at $2.65. The stock touched about $2.63 on Oct. 22, then closed at $2.625 on October 23, 2026.
The adviser appointments do not establish that bankruptcy or major operating changes are imminent. There is no indication that the airline’s current schedule or onboard offerings will change.
Creditors often bring in financial and legal advisers when they see a risk that a borrower may not repay on schedule. The holders’ move comes amid a steep decline in JetBlue securities.
The creditor group holds bonds and a first-lien loan
The group includes bondholders and lenders. Their positions include:
| Creditor position | Amount and terms |
|---|---|
| Bonds | $2 billion, due 2031 |
| Loan | $742 million, first-lien loan |
A separate market measure shows pressure across the debt. Loyalty-backed bonds lost 10 cents in a week to about 45 cents on the dollar; the first-lien loan fell 13 cents to 45 cents.
Shares have lost about 58% since the start of August, fallen roughly 40% in a month and dropped 42% this year. Short interest has climbed above 30% of the shares available to trade.
Airline debt investors have been watching for distress since Spirit Airlines shut down operations earlier this year after repeat bankruptcy filings. The price moves add to concern, but they do not determine whether JetBlue will seek court protection.
Cash, collateral and fuel costs frame the repayment risk
At June 30, JetBlue held $1.66 billion in cash and cash equivalents, against $8.5 billion in debt and finance lease obligations. A significant share of that debt is backed by the aircraft fleet and TrueBlue loyalty program.
Quarterly filings show roughly two-thirds of the airline’s property, equipment and intangible assets pledged as collateral. In April, it secured about $500 million in aircraft-backed capital, fully drawn by June 30.
The airline said it had no credit-card processor collateral requirements at the end of June. Processors can require airlines to set aside collateral if financial conditions worsen. That disclosure describes the position at that date, not a guarantee about future requirements.
Fuel prices have added pressure. US jet fuel prices nearly doubled from late February amid the Iran war, even as airfares rose and travel demand remained steady. JetBlue’s average fuel price jumped 76% to $4.23 per gallon in the second quarter.
The airline raised its third-quarter fuel-cost estimate in September. Like most major US airlines, it does not hedge a significant amount of its fuel. In the second quarter, JetBlue posted a $247 million net loss while revenue rose 14.5% year-on-year to $2.7 billion.
Ratings agencies forecast more losses and a cash deficit
Moody’s cut JetBlue’s rating to Caa2 in May and forecast operating losses this year and next. S&P lowered its rating to CCC+ in a June note and projected a free cash flow deficit of about $1 billion for 2026.
S&P Global Ratings recently downgraded the airline, citing higher fuel costs. The ratings are agency assessments; they do not by themselves establish that the airline will file for bankruptcy.
JetBlue is pursuing cost cuts and a premium-cabin expansion
The airline has spent the past two years working on JetForward, a plan launched in July 2024 under CEO Joanna Geraghty. It focuses on cost control and making better use of the airline’s network and aircraft.
JetBlue is also carrying out a financial and operational overhaul and plans to expand premium offerings. A company representative said it was “focused on strengthening revenue and building a more profitable business.” The airline has also said it “remains confident in its JetForward strategy” and pointed to progress toward sustained profitability.
Bookings opened this month for BlueFirst, a domestic first-class cabin on flights without the airline’s Mint business-class product. The cabin is planned for more than 30 routes. Its first service is scheduled between Boston Logan (BOS) and Fort Lauderdale (FLL) on December 8, with wider recliner seats among the perks.
The earnings call will put the turnaround and sale speculation in focus
JetBlue plans to update its financial outlook and progress during its third-quarter earnings call. Consensus expects a loss of roughly 53 cents a share on revenue of about $2.83 billion. Management’s stated goal is a $1.00 EPS 2028 target.
Reports earlier this year said the airline had explored a possible sale to another carrier. United, Alaska Airlines and Southwest Airlines were named as potential buyers. United CEO Scott Kirby, asked about JetBlue on a recent earnings call, said he had “nothing new to add on that.”
JetBlue’s market capitalization is about $990 million. Equity remains a residual claim after secured lenders and bondholders are paid. Roughly $6 billion in unencumbered assets face pledging pressures, while one market analysis argued that the stock could be worth near zero. That is commentary, not an official determination.
The company is scheduled to report third-quarter results before the market opens Tuesday, Oct. 27.