How Gold Sales Are Taxed on Capital Asset Gains Over the Holding Period
India’s tax treatment of gold-sale profits turns on the product, how long it was held and whether it came through a gift or inheritance.
At a glance
- Gold gains require Schedule CG reporting in the return for the financial year of sale.
- Gold ETF management fees carry 18% GST, reflected in the expense ratio.
- Gifted gold from a non-relative is taxable in full when its value exceeds ₹50,000.
Reviewed October 29, 2026
Indian tax rules calculate gains from gold sales according to the product and how long the seller owned it. Gold counts as a capital asset, and sellers generally must report a profit in their income tax return.
The holding period test differs across jewellery, digital gold and investment products. Selling gold is not always taxed like selling a fund unit, and some bond income is treated separately from a sale gain.
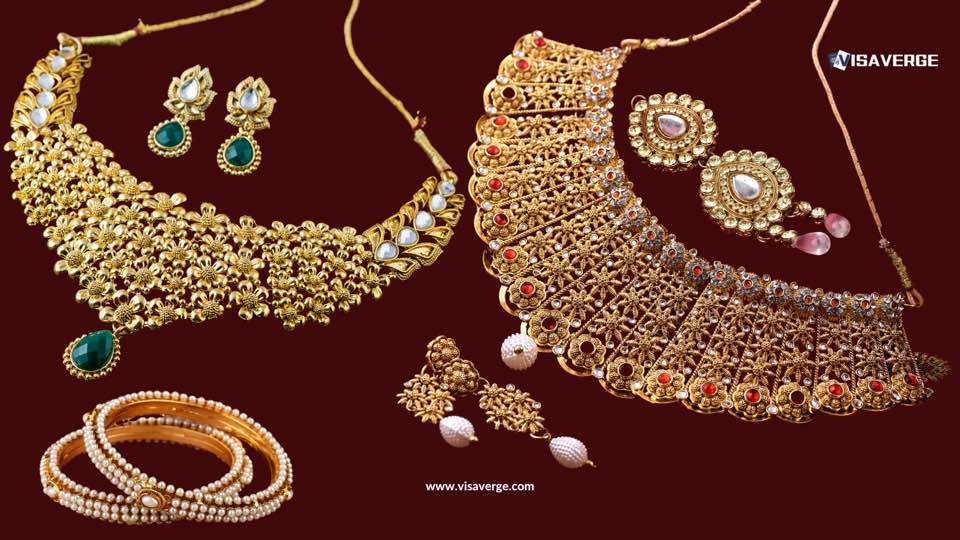
These rules cover physical jewellery and investment holdings, including gold ETFs, mutual funds and Sovereign Gold Bonds (SGBs). The applicable treatment depends on what was sold and the seller’s circumstances.
A gain on sale and tax paid when buying gold are separate matters. The purchase of jewellery or digital gold can attract GST, while selling personal old jewellery to a dealer generally does not.
Gifted and inherited gold also require attention to the previous owner’s purchase cost and, in some cases, their time holding the asset. A sale can create a taxable gain even when the recipient owed no tax when receiving the gold.
The rules also distinguish investment income from sale proceeds. SGB interest, for example, is taxed as income rather than as a capital gain.
Gold products follow different holding-period tests
| Gold holding | Shorter holding or income treatment | Longer holding or maturity treatment |
|---|---|---|
| Physical gold and jewellery | Sale gain is taxed at the individual’s slab rate through 24 months | After 24 months, the long-term capital asset rate is 12.5% plus 4% cess, without indexation, for transfers on or after July 23, 2024 |
| Digital gold | Sale gains follow the physical-gold treatment | Long-term treatment follows the physical-gold rule |
| Gold ETF units listed on a recognized Indian stock exchange | Gains on holdings of 12 months or less are taxed at the investor’s slab rate | After 12 months, gains face 12.5% plus applicable surcharge and cess, without indexation; the Rs 1.25 lakh equity-gain exemption does not apply |
| Gold mutual funds and fund of funds | The material does not specify a separate short-term rate | More than 24 months is required for long-term gains |
| Sovereign Gold Bonds | Annual interest is taxed as “Income from Other Sources” at the investor’s slab rate | Specific tax exemptions apply if the bonds are held until maturity |
SGBs pay 2.5% annual interest, and that interest is fully taxable. It is separate from the bond’s capital-gains treatment.
A sale can trigger tax even when the gold came as a gift
When gold passes through inheritance, the recipient generally uses the previous owner’s purchase cost and can add that owner’s holding time to their own. If the original purchase cost cannot be established, fair market value on April 1, 2001 may be used where applicable.
A gift received at marriage, or a gift from specified relatives such as parents, is not treated as income when received. But a later sale can trigger capital-gains tax. The calculation uses the previous owner’s acquisition cost and combines the owner’s and recipient’s holding periods.
Balwant Jain, a Mumbai-based CA and CFP, said long-term gains on jewellery may be exempt when the seller invests the net sale proceeds in a residential house under Section 86 of the Income Tax Act, 2025. The exemption is available only if the seller does not own more than one residential house on the jewellery’s sale date.
A gift of physical gold from a non-relative has a different tax test. If its fair market value exceeds ₹50,000, the full value is taxable to the recipient as “Income from Other Sources.” Inherited gold is not taxable on receipt.
Purchase GST and sale reporting are separate questions
Finished jewellery attracts 3% GST on the full transaction value, including making charges, even if the invoice lists those charges separately. An individual’s sale of personal old gold to a jeweller is generally outside GST when the seller is not carrying out a business transaction.
Buying digital gold also attracts 3% GST on the transaction value. Investors do not pay GST when buying gold ETF or mutual-fund units; GST charged on fund management fees is reflected in the expense ratio. ETF management fees carry 18% GST.
Chintan Ghelani, Partner–Direct Tax at N. A. Shah Associates LLP, described the long-term rate for physical gold as “12.5%, plus applicable surcharge and cess, without indexation benefit.”
Gold-sale gains cannot be entered in ITR-1. Sellers generally need ITR-2; those with business income may need ITR-2 or ITR-3. The gain belongs in “Schedule CG” for the financial year of the sale.
Keep the purchase invoice, sale receipt and bank statements to support the return. Gold purchases and sales often cluster around Dhanteras and Diwali, but the relevant tax year is the one in which the sale took place.
Keep reading
More in Questions → Documentation · Jul 15
FY 2025-26 Investment Tax Guide: Shares, Mutual Funds, Securities Transaction Tax Explained
Master India's 2025-26 tax rules. Learn about the 12.5% capital gains rate, Section 50AA debt fund changes, and NRI reporting for AY 2026-27.
 Guides · Oct 26
Gold at Home: Income-Tax Rules and the 500-Gram Figure Under CBDT Instruction No. 1916
 India · Oct 26
India Weighs Long-Term Capital Gains and Securities Transaction Tax Changes in Union Budget
India · Sep 11
15 Tax-Free Incomes in India for 2026: Gifts, Inheritance, PPF, EPF, Agricultural Income Explained
-
 Questions How IRS Rules Apply to Unmarried Couples Filing a Joint Return
-
News Finland Targets 14-Day Fast-Track Residence Permit Decisions via Enter Finland for EU Blue Card and Other Work Categories
-
Immigration 1 in Absentia Removal Order Risk Follows Latest Official Notice from Executive Office for Immigration Review